Quick Facts
Introduction
Complete guide to the Wazir-e-Azam Apna Ghar Program 2026: eligibility, up to Rs 10 million financing, 5% markup, property limits, documents, apply link, banks and last-date status.
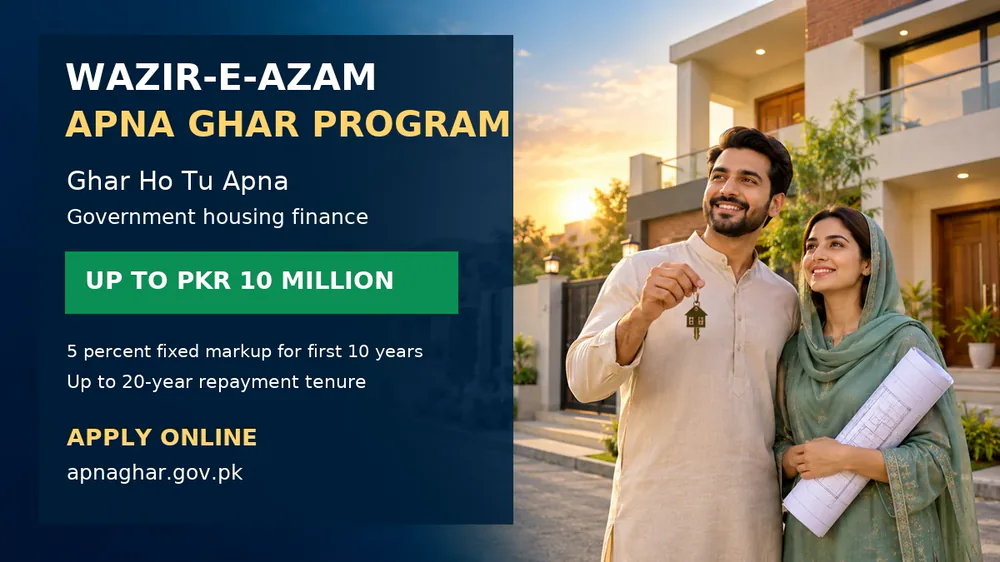
Wazir-e-Azam Apna Ghar Program 2026 is designed to help eligible first-time homebuyers in Pakistan access subsidised housing finance. The official programme is also known as “Ghar Ho Tu Apna”. Applicants can use apnaghar.gov.pk to create an account, check the programme information, submit a loan application and track its progress.
For related updates, explore Banking Info, Scholarships, Jobs and for more information.
This is a government-supported housing loan, not a free-house or cash-grant scheme. The bank or other participating institution makes the final credit decision after verifying the applicant, income, property documents, repayment capacity and other applicable conditions. Registration or form submission does not guarantee approval.
Wazir-e-Azam Apna Ghar Program 2026: Main Features
| Official programme name | Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna |
|---|---|
| Maximum financing | Up to PKR 10 million (1 crore) |
| Customer markup | 5% fixed for the first 10 years; the remaining period is subject to the applicable market-rate terms |
| Maximum tenure | Up to 20 years |
| Bank financing ratio | Up to 90% financing; normally 10% applicant contribution |
| House size | Up to 10 Marla or 2,720 square feet, according to the official programme information |
| Apartment size | Up to 1,500 square feet |
| Processing fee | No processing fee listed by the official portal |
| Prepayment penalty | No prepayment penalty listed by the official portal |
| Apply through | Official online portal and participating banks, Islamic banks, microfinance banks, HBFC and participating NBFCs |
What Housing Purposes Are Covered?
The official Apna Ghar portal lists several financing categories. An applicant may use the programme, subject to bank approval and the applicable terms, for:
- Purchase of a house or flat: Buy an eligible ready-to-move-in residential property.
- Plot plus construction: Purchase a residential plot and finance construction under the combined facility, within the permitted property limits.
- Construction: Build a new house on a residential plot already owned by the applicant.
The property must satisfy the bank’s legal, valuation, mortgage and location requirements. Before paying an advance or token money, applicants should ask the selected bank to confirm whether the title, transfer status, approved map, valuation and construction plan are acceptable.
Eligibility Criteria for Apna Ghar Loan
The official portal identifies first-time homebuyers with a valid CNIC who do not already own a housing unit as the primary eligible group. The programme terms also state that eligibility is subject to the published rules, including age, income, identity verification and property-ownership requirements.
- The applicant should be a first-time homebuyer and should not already own a house or flat in his or her name.
- The applicant must provide a valid CNIC and pass identity verification.
- The applicant must meet the participating institution’s age, income, credit and repayment-capacity requirements.
- The applicant must provide accurate personal, employment, financial and property information.
- The proposed house, flat or plot-plus-construction transaction must fall within the programme’s size and financing limits.
- The applicant must not submit false, forged, incomplete or misleading documents.
- Overseas Pakistanis holding NICOP or POC may also be eligible under the multi-channel implementation instructions, subject to the applicable bank and programme conditions.
Income, Debt Burden and Bank Assessment
The portal’s loan calculator includes an income field and describes the result as indicative only. Actual approval depends on the applicant’s documented income, existing loans, monthly expenses, employment or business profile and the selected institution’s underwriting policy.
State Bank of Pakistan instructions state that total monthly amortisation payments, including the proposed housing finance and other consumer-finance obligations, should not exceed 65% of the applicant’s net disposable income. This is a bank-assessment rule, not a promise that every applicant will qualify for the maximum loan amount.
Loan Amount, Markup and Repayment Terms
The maximum financing shown by the official portal is PKR 10 million. The customer markup is listed as 5% fixed for the first 10 years. The total repayment period can extend up to 20 years; after the fixed-rate period, the remaining tenure is subject to the applicable market-rate terms and the agreement signed with the participating institution.
The portal’s calculator can provide an indicative estimate based on income, debt-burden ratio and tenure. It is not a sanction letter. The final monthly instalment, insurance or takaful treatment, legal expenses, valuation costs, equity contribution and other charges must be confirmed in writing from the selected bank before signing.
90:10 Financing and Applicant Contribution
The official programme information lists up to 90% loan-to-value financing, which means an applicant may generally need to arrange around 10% of the eligible property or project cost from personal resources. The exact contribution can change after valuation, because banks normally finance against the eligible assessed value and approved cost—not an inflated asking price.
Required Documents for Application
The online form and participating institution will display the final document checklist for each applicant. Prepare clear and valid copies of the following information where applicable:
- CNIC for the applicant and any required co-applicant.
- Recent photographs and active mobile number or email for verification.
- Proof of income, salary slips, employment record or business-income evidence.
- Bank statements or other financial information requested by the institution.
- Property title documents, ownership record, sale agreement or approved plan, depending on the financing purpose.
- Plot documents and construction plan for plot-plus-construction or construction cases.
- NICOP or POC and overseas income or residence evidence for eligible overseas applicants.
- Any declaration confirming first-time homebuyer status and non-ownership of a housing unit.
Do not upload edited, blurred or mismatched documents. The name, CNIC number, address and ownership details should be consistent. The bank may ask for additional documents during verification or property assessment.
How to Apply Online at apnaghar.gov.pk
- Open the official website: apnaghar.gov.pk.
- Select Start Now or open the official registration page at apnaghar.gov.pk/auth/register.
- Create an account with the CNIC, name, mobile number, email and password requested by the portal.
- Log in and complete the loan application form accurately.
- Select the relevant purpose: house or flat purchase, plot plus construction, or construction on an owned plot.
- Provide income, financial, property and contact information and upload the requested documents.
- Review the declaration and all entered details before submitting the application.
- Save the application number, acknowledgement, screenshots and any downloadable receipt.
- Track the status through the portal and respond promptly if the selected institution requests clarification.
Can You Apply Through a Bank?
Yes. The official programme provides multiple channels. Applicants can apply through the online portal or approach a participating commercial bank, Islamic bank, microfinance bank, HBFC branch or participating NBFC. The current official portal displays participating institutions, including banks such as Bank of Punjab, National Bank of Pakistan, Meezan Bank, HBL, UBL, Allied Bank and other listed institutions.
Use only a branch, website or contact channel verified from the official portal. A bank employee can guide you through the formal process, but no person can guarantee approval before the credit and property assessment is complete.
Processing Time and Application Status
The State Bank of Pakistan has instructed banks and HBFC not to take more than 15 working days for credit approval after receiving a complete application with complete information. This is not a guarantee of disbursement within 15 days; missing documents, valuation, legal scrutiny, income verification or property issues can affect the timeline.
Check the online dashboard and keep the bank’s acknowledgement safe. If the application is returned for correction, submit the required information through the official channel and do not create duplicate applications without guidance.
Apna Ghar Program 2026 Last Date
No fixed public closing date is shown on the official Apna Ghar portal at the time of this article’s verification on 20 October 2026. The official website provides a live registration and application route, but applicants should not interpret this as a permanent guarantee that the programme will remain open without changes. The government and participating institutions may update terms, quotas, application channels or availability.
Applicants should apply as soon as they are ready with complete documents and should check the official portal before submitting. Ignore social-media posts claiming an unverified “last date”. A genuine deadline or temporary closure should be confirmed on apnaghar.gov.pk, through the selected participating institution or through an official government/SBP notice.
Important Benefits of the Scheme
- Access to subsidised housing finance for eligible first-time homebuyers.
- Financing of up to PKR 10 million under the official programme limit.
- 5% fixed customer markup for the first 10 years.
- Up to 20 years of repayment tenure.
- Up to 90% financing, subject to valuation and bank approval.
- Multiple housing purposes, including purchase, construction and plot plus construction.
- Online registration, application and status tracking.
- Multiple commercial, Islamic, microfinance and housing-finance institutions.
- No processing fee and no prepayment penalty listed by the official portal.
Safety Tips for Applicants
- Use only the domain apnaghar.gov.pk and an institution listed on the official portal.
- Never share an OTP, password or full account credentials with an agent.
- Do not pay anyone who promises guaranteed approval, a reserved quota or faster disbursement.
- Confirm any fee, bank account, valuation charge or legal cost directly with the selected institution.
- Do not transfer money to a personal account or an unofficial mobile-wallet number.
- Keep copies of forms, property papers, bank acknowledgements and payment receipts.
Official Links
- Official Apna Ghar Portal
- Create Account / Register
- Official Loan Details and Calculator
- SBP Multi-Channel Implementation Instructions
- SBP Processing and Debt-Burden Instructions
Source and update note: This article was prepared after reviewing the official Apna Ghar portal, its registration and loan-details pages, and relevant State Bank of Pakistan instructions. Programme terms, bank lists, eligibility conditions, rates and application availability can change. Confirm the latest information from the official portal or participating institution before applying. For more government programmes, visit our Govt Schemes category.
FAQs
What is the Wazir-e-Azam Apna Ghar Program?
It is a federal subsidised housing-finance programme known as “Ghar Ho Tu Apna”. It helps eligible first-time homebuyers access financing through the official portal and participating financial institutions.
How much loan can I get?
The official portal lists maximum financing of up to PKR 10 million. The approved amount depends on income, debt obligations, property value, valuation, documents and the participating institution’s assessment.
What is the markup rate?
The official programme information lists a 5% fixed customer markup for the first 10 years. The remaining repayment period is subject to applicable market-rate terms and the financing agreement.
Who is eligible to apply?
First-time homebuyers with a valid CNIC who do not already own a housing unit may apply, subject to age, income, identity, property and bank-assessment requirements. Eligible overseas Pakistanis with NICOP or POC may also apply under the applicable rules.
What is the last date to apply?
No fixed closing date is shown on the official portal as of 20 October 2026. Check the official website and selected participating institution for any future deadline, temporary closure or change in availability.
Is this a free-house scheme?
No. It is a subsidised housing-finance or loan programme. Approved applicants repay the financing according to the agreed tenure, markup and bank terms.
How long can the bank take to process a complete application?
SBP instructions state that banks and HBFC should not take more than 15 working days for credit approval after receiving a complete application with complete information. Property, legal and document issues can affect the overall timeline.
Conclusion
Review the official sources, dates and eligibility conditions mentioned in this article before taking action. For more related updates, explore the category links above.
Comments (0)
No Comments Found